Starter guide

Newly licensed loan officer? Your starter website guide.

Congratulations on the license. Your first website should prove three things fast: who you are, that you're licensed (with your NMLS ID), and how a borrower or agent starts a conversation with you. This guide covers what to show, the first 30 days, and a realistic budget.

Mortgage loan originator

Your Name Here

NMLS ID •••••••

Status: Approved

Tavi the hare mascot jumping for joy holding a blank license card (no text) with a small mint ribbon — celebrating a brand-new license.

01 What does a new loan officer's first website have to do?

It has one job: turn "who is this?" into a conversation. That means a real photo and bio, proof you're licensed, the programs you help with, and two easy next steps — apply or book a call.
Who you are

Photo, a bio that sounds like you, where you work and who you love helping.
That you're licensed

Your NMLS ID, your company's, and your licensed states — linked for verification.
How to start

A short application, calculators and a booking link that work on a phone.

02 What must a loan officer website show?

The usual set, which your company and state rules may extend:

  • Your individual NMLS ID and your company's name and NMLS ID
  • The states you're licensed in, worded the way your company requires
  • Equal Housing Opportunity (or Equal Housing Lender, depending on your company)
  • Privacy notice and a way to opt out of marketing
  • No rates or payments without the full disclosures (Regulation Z §1026.24 "trigger terms")

This is an educational summary, not legal advice. Check any page against our free compliance checklist, and read the source: Regulation Z §1026.24.

03 Your first 30 days online

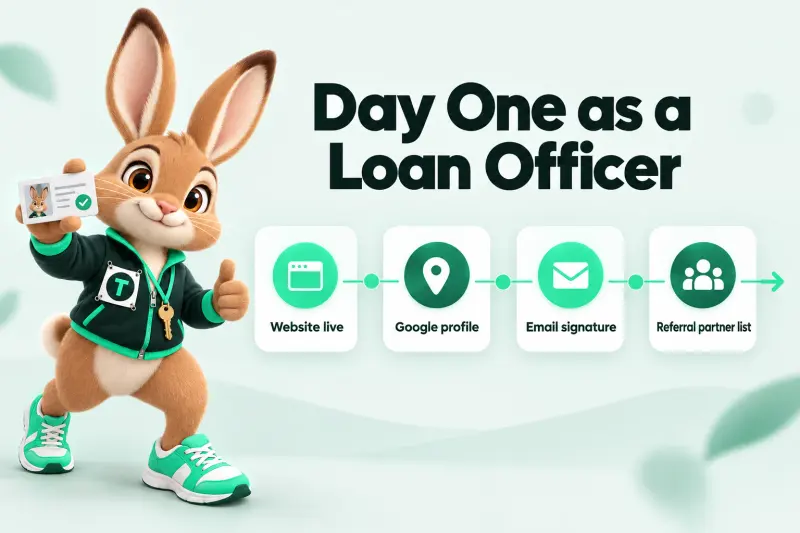
Infographic: Day One as a Loan Officer — Website live; Google profile; Email signature; Referral partner list. Tavi the hare mascot holding up a fresh license card proudly.
  1. Week 1

    Go live

    • Website live with your NMLS ID and company lines
    • Email signature with the link
    • LinkedIn and Facebook bios updated
  2. Week 2

    Be findable

    • Google Business Profile, if your company allows one
    • Ask 5 people who know your work for a review
    • Share one helpful post (not a rate)
  3. Week 3

    Partners

    • List 20 real estate agents and builders you know
    • Send each a short intro with your site link
    • Offer a co-branded calculator page (with compliance approval)
  4. Week 4

    Follow-up

    • Every lead in one CRM inbox
    • A simple follow-up sequence for new leads
    • Decide: funnels, blog content or the AI receptionist next

04 What does a starter online presence cost?

With us, the core is one monthly plan. Everything else is optional and one-time. Here's a realistic starter budget using our prices.

Our prices as of the pricing page date; domain registration is paid to your registrar and varies.
ItemNeeded?Cost
First Desk website planYes$79/mo + $249 setup (waived yearly)
Domain nameRecommendedRegistrar's price, in your name
Headshot-ready bio + headshot briefHelpful$89 one-time
Google Business Profile setupIf your company allows$129 one-time
Logo mini-kitOptional$189 one-time
CRM follow-up (First Desk)Recommended by month 2$49/mo
Day-One Desk (site + AI receptionist)If you can't take calls all day$199/mo

05 Company profile page or your own website?

 Company profile pageYour own site
Cost to youUsually freeMonthly plan
Moves with you if you switchNoYes (domain in your name)
Ranks for your nameSometimesBuilt to
Your own calculators, funnels, blogRarelyYes
Compliance approval neededDone by companyYes — we prepare the packet

Many LOs keep both: the company page for the company's site, their own site for everything they share.
06 Five mistakes new loan officers make online

  1. Waiting until the first closing

    Agents and borrowers check you online before they call. A missing website reads as "not ready".

  2. Posting rates on social

    A rate or payment in a post can trigger full Regulation Z disclosures. Talk about programs and process instead, and get approval.

  3. Using the company template only

    Fine as a start, but you can't take it with you, and it rarely ranks for your name.

  4. Leaving off the NMLS ID

    Your individual NMLS ID belongs on your site and ads. Borrowers can verify it on NMLS Consumer Access.

  5. No follow-up system

    A lead that waits until tomorrow often calls someone else. Even a simple automated reply helps.

Suburban houses on a green hillside under a cloudy sky

FAQ

New loan officer questions

Does a newly licensed loan officer need a website?

Not legally, but practically yes. Referral partners and borrowers search your name before they trust you with a file. A simple, compliant site with your bio, NMLS ID, calculators and an application tells them you're ready, even before your first closing.

Can I build my website before my license is approved?

We can draft it, but it stays private until your license and company sponsorship show on NMLS Consumer Access. Advertising loan origination before you're licensed is a problem we won't help create.

What should a new loan officer put on a website?

Your name, photo and a short honest bio; your NMLS ID and your company's; licensed states; the loan programs you work with; calculators; a way to apply or book a call; and the required disclosures. Skip rate claims until your compliance team approves them.

How much does a starter loan officer website cost?

Our First Desk plan is $79/mo (or $67/mo billed yearly, 15% off with setup waived). DIY builders cost less per month but you write, design and check compliance yourself — see our Wix comparison.

Launch day in 5 business days

New license, new website, this week.

First Desk gets you live in 5 business days with everything a new LO needs to look established.

No payment on the form · Monthly plans cancel any time · Reply within 4 business hours